
Opinion
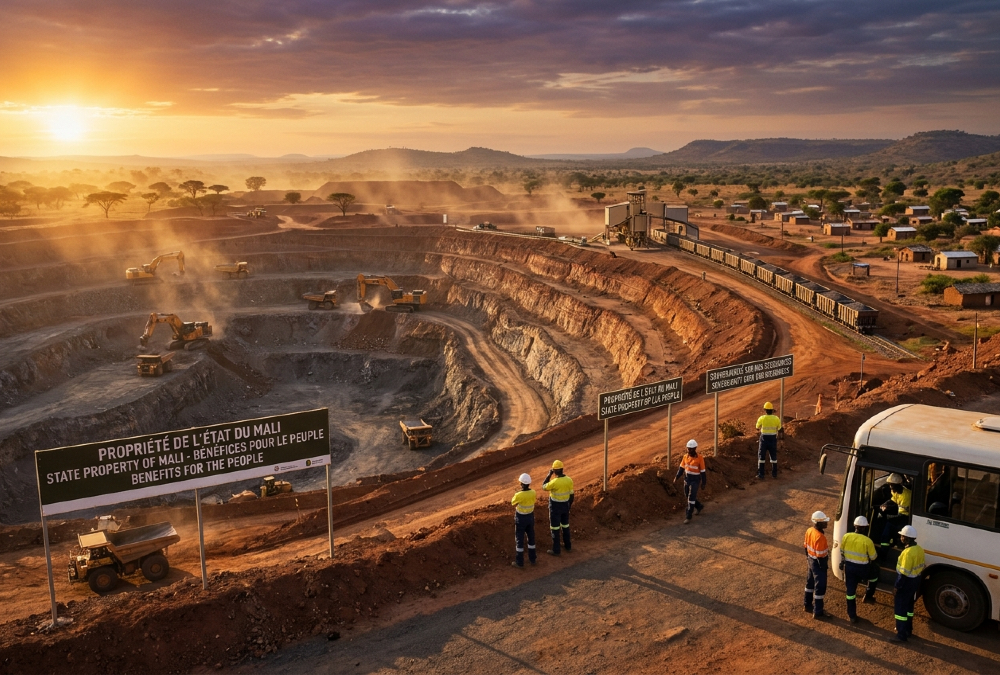
The Wealth Beneath Our Feet
By Daki Nkanyane
“Dependent nations can never be considered developed.”
Walter Rodney wrote those words in How Europe Underdeveloped Africa (1972), a book about an economy in which African labor and resources enriched others while Africa’s own productive capacity stayed stunted. The sentence belongs to its era. The question behind it does not: how much control does an economy have over the wealth it helps create? No table of mineral output can answer that.
The question returned to me at the African Review of Economics and Finance (AREF) conference, where Professor Imhotep Alagidede spoke. This year’s theme, “Owning the Ground Beneath Our Feet”, put resource sovereignty and African wealth creation at the center of the debate. This series takes up that invitation, following the public evidence from sub-Saharan Africa’s mineral regions to the Cape. The interpretations are my own.
What the Ground Contains
The scale is considerable. The United States Geological Survey (USGS) estimates that the Democratic Republic of the Congo supplied about 73 percent of the world’s mined cobalt in 2025. Its 2026 commodity summaries name Guinea as the leading bauxite producer and South Africa as the leading producer of platinum and, by manganese content, of manganese ore. But these are estimates of production, not measures of the money that reaches citizens.
Travel south and the mineral map grows more crowded: Zambia’s copper, Zimbabwe’s lithium and platinum, Namibia’s zinc, Botswana’s diamonds and the mining regions of South Africa. Madagascar and Mozambique also figure in the graphite economy. Each resource has its own markets, technical demands and environmental costs. A strategy that suits copper cannot simply be copied for diamonds.
That diversity matters, because “Africa’s mineral wealth” conceals as much as it reveals. A government negotiating over a large, commercially proven deposit faces a different choice from one weighing a promising geological find. Countries also differ in their ability to finance infrastructure, collect revenue and enforce obligations.
A Deposit Is Not a Bank Balance
There is a tempting calculation in public debate: multiply the estimated mineral underground by its current market price and announce a national fortune. It produces impressive headlines and unreliable policy.
Some material cannot be recovered economically. Some will take decades to extract. Capital, energy and rehabilitation have to be paid for. Prices will change. Investors, workers, suppliers and governments receive different portions of the eventual proceeds. A reserve estimate therefore cannot be treated as cash that a treasury has inexplicably failed to withdraw.
The World Bank’s Changing Wealth of Nations provides a more useful distinction. GDP measures production over a period. Comprehensive wealth considers the assets that support future production, including natural resources, human capabilities and produced assets. Extraction can raise output while reducing the stock of a finite resource. Whether a country becomes durably wealthier depends partly on what it builds with the proceeds.
This changes the standard by which success should be judged. An export increase matters, but so does whether the resulting income finances reliable infrastructure, healthier people and businesses capable of surviving beyond the mine.
Following the Conversion
The real investigation begins between the deposit and the household. Who can establish what lies underground? Who finances its development? Which contracts determine the return? How much reaches the budget, and what does public spending accomplish?
These questions explain why geological abundance predicts so little. A poorly designed tax regime can surrender public revenue. A sound one can still disappoint if production is disrupted. And revenue that is collected can be squandered on projects that cost more to maintain than they deliver in benefits.
None of these failures is inevitable. In “Institutions and the Resource Curse” (2006), Halvor Mehlum, Karl Moene and Ragnar Torvik examined how institutional conditions determine whether resource income encourages production or a scramble to appropriate existing wealth. Their findings undermine a deterministic reading of resource abundance, though they do not explain every country’s troubles.
History matters, but it is not destiny. Colonial-era extraction left behind institutions, infrastructure and trade patterns that deserve close scrutiny. Yet governments and firms today make consequential choices of their own. To blame every disappointing outcome on colonial history is to excuse decisions that can still be changed. To treat history as irrelevant is to make those decisions harder to understand.
The Argument Against Complacency
A fair objection is that mining already creates jobs, foreign exchange and tax revenue. It does. To demand that every mine deliver a full industrial transformation would set a test that few investments anywhere could pass.
Yet citizens are entitled to ask whether a given deal pays an adequate return for the asset surrendered and the risks borne. Answering that requires an honest comparison with realistic alternatives, including the option of waiting. Immediate extraction is one choice among several, particularly where infrastructure is weak or environmental damage would be hard to reverse.
The question grows sharper as the energy transition turns the spotlight on particular minerals. The UN Conference on Trade and Development (UNCTAD) has identified opportunities in processing and supplier industries, alongside obstacles in infrastructure, technology and market access. Demand opens a door. Walking through it takes deliberate work.
An Account That Citizens Can Read
Every major resource project should come with a public account of its expected contribution. Citizens should be able to compare projected revenue with actual revenue, see who owns what, and track obligations to neighboring communities. Forecasts should show what happens when prices fall or costs rise.
Such an account would hold political claims to the standard of evidence. A minister announcing an investment could be asked which domestic capabilities the agreement finances. A company advertising community benefits could be asked whether they are additional, measurable and lasting. A state-owned enterprise claiming strategic importance could be asked what its ownership delivers after financing costs.
Rodney’s warning does not oblige us to accept his entire account of the world. It does oblige us to scrutinize the terms on which we take part in it.
The deposits will not stay underground forever. Some will be exhausted; others may lose their commercial value before a single tonne is extracted. The window to turn them into something durable is narrow.
When our children ask what became of the wealth beneath their feet, will we be able to show them what it built, or only how much of it we sold?
Daki Nkanyane is a South African-born Pan-African thought leader, entrepreneur, strategist and keynote speaker with 28 years of business experience across Africa and Europe. He is the Founder and Executive Chairman of Interflex Capital, a growth and capital advisory firm that helps mid-market and established organisations turn growth ambition into enterprise value. His advisory work focuses on strategy execution across mobility, mining, financial services and media. A practitioner-scholar, he is completing a Master of Management in Entrepreneurship and New Venture Creation (MMENVC) at Wits Business School, where he is also a guest lecturer and executive education coach. He is a professional member of IMCSA
