
Opinion
Beyond the Ground: The Architecture of Africa’s Economic Sovereignty
Africa’s 18 state-owned sovereign wealth funds hold roughly $162 billion – about 1.2 percent of global sovereign fund capitalization. The temptation is to ask why the pot is so small. The more revealing question is what happens to the money once it enters the system.
By Dishant Shah
Africa’s oil story is not about what lies beneath the ground. It is about how much economic value stays above it.
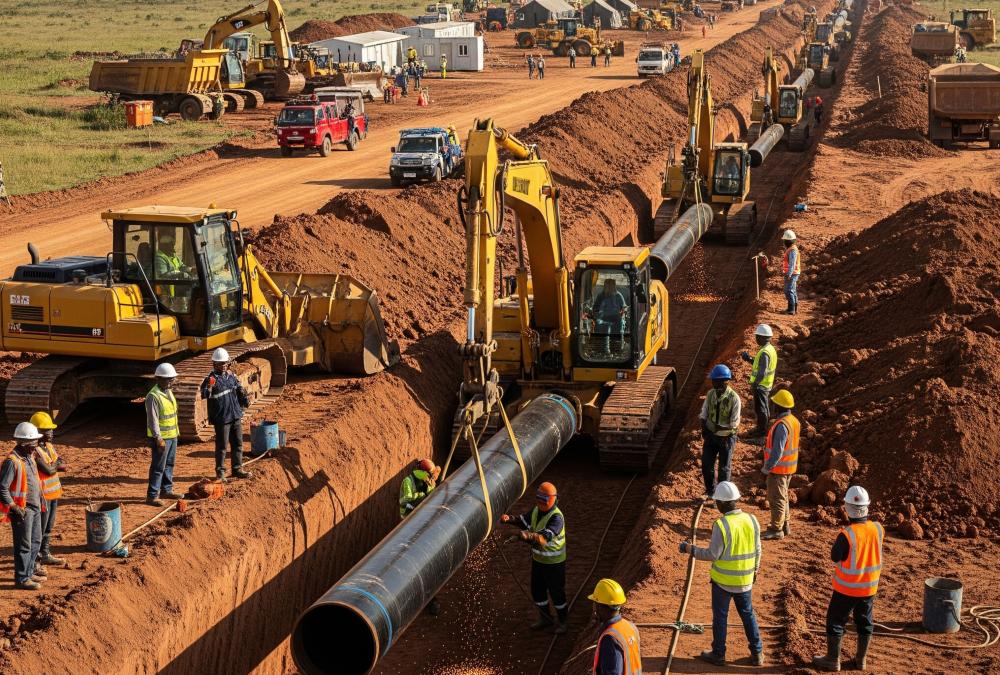
Finding oil is the easy part. Namibia’s offshore Orange Basin has drawn TotalEnergies, Shell and Galp. Uganda is edging toward commercial production from the Albertine Graben, with the Kingfisher and Tilenga projects and the East African Crude Oil Pipeline forming the spine of a new petroleum industry. Both countries have glimpsed a prize. Neither has yet shown it can keep it.
History is unkind to the optimists. Windfalls are announced with fanfare and spent with haste. Prices reverse, costs overrun, and a discovery that promised transformation delivers a temporary consumption boom followed by austerity. The real measure of a resource is not the revenue it generates but the productive capacity, fiscal strength and economic resilience a country builds with it. Three questions determine which outcome a nation gets.
First: How Much Value Stays at Home?
Royalties and taxes matter, but they are only the most visible slice of an oil economy. Local suppliers, skilled employment, engineering know-how and supporting industries are where lasting value accumulates. A country that exports crude while importing most of its equipment, expertise and finished goods captures only part of the opportunity, and often the least durable part.
Local content is not a slogan to be stamped onto contracts. Forcing domestic participation without building the capability to deliver it merely inflates costs and rewards the well-connected. The harder and more rewarding work is cultivating suppliers and a workforce capable of competing, so that the industry’s skills outlive any single field.
Second: Who Controls the Economics?
Frontier exploration is expensive and risky, and foreign capital and technical expertise are often indispensable. Foreign investment is not the problem. Poorly structured incentives and weak accountability are.
The test for governments is institutional rather than ideological. Can they negotiate commercially sound agreements, collect revenue efficiently and build the capacity to protect the public interest across decades-long projects? A well-drafted contract is worth little to a state that cannot monitor, audit or enforce it. Ownership matters less than the quality of the institutions doing the owning.
Third: What Happens When the Oil Runs Out?
Oil is a finite asset, and this is where sovereign wealth funds enter the story. They exist to turn finite natural resources, fiscal surpluses and public wealth into financial resilience that outlasts the current generation.
According to the African Development Bank Group, Africa had 18 state-owned sovereign wealth funds with combined capitalization of US$162 billion in March 2025. That is roughly 1.2 percent of global sovereign wealth fund capitalization. The obvious reaction is to ask why African funds are so small. The more interesting question is what happens to the money once it enters the system.
Three decisions determine whether sovereign wealth becomes national wealth.
What gets saved? Governments that spend every windfall during a boom often rediscover the joys of austerity when prices fall. A stabilization fund smooths the cycle, while an intergenerational fund preserves wealth beyond the depletion of the resource that created it. The distinction is easily blurred but important: one protects tomorrow’s budget, the other protects tomorrow’s citizens.
Where does the money go? Investing abroad is not a failure of domestic development. Diversification stops a fund from concentrating its capital in the very economy that generates its revenues. Yet the opposite extreme is just as damaging. Forcing every investment into domestic projects, regardless of risk or return, turns a sovereign wealth fund into a politically directed lending vehicle. The objective is not to keep every dollar at home. It is to maximize long-term national value.
Who decides, and who holds them accountable? Here the real institutional test begins. Transparent mandates, independent investment decisions, credible audits and clear rules governing withdrawals matter more than impressive launch announcements. A fund can accumulate billions and still fail its purpose if capital allocation follows political convenience rather than economic merit.
Nigeria’s Sovereign Investment Authority, Angola’s Fundo Soberano de Angola and Morocco’s Ithmar Capital illustrate different approaches to public investment, diversification and economic development. Their mandates and structures differ, so headline asset figures alone cannot tell the whole story. A fund’s size says little about its quality.
The Uncomfortable Arithmetic
There is a less comfortable reality that both oil producers and fund managers must face. Infrastructure costs, volatile prices, environmental risks and project delays can all erode returns that looked irresistible on the day of discovery. Roads, ports, electricity networks, industrial capabilities and a skilled workforce can generate returns long after production declines, but only if the money is converted into productive assets rather than spent on a temporary boom.
Namibia and Uganda have different starting points, but they face the same fundamental test: can petroleum become a catalyst for broader economic development? The answer will not be found in reserve estimates or launch ceremonies. It will be found, decades from now, in whether the country owns more than it did before the oil came.
The Measure That Matters
Sovereign wealth is not measured only by what a country owns today. It is measured by what that wealth enables the country to own tomorrow: productive businesses, strong public finances, better infrastructure and a broader base of private investment.
That is the question African policymakers should be asking. It is not how much resource revenue they can capture, but how much lasting economic value they can create from every dollar they capture. The true return on natural resources is the productive capacity left behind when the resources are gone.
Dishant Shah is a partner at Legion Exim, a company specializing in facilitating the export of high-quality engineering products directly sourced from manufacturers in India to Africa. His areas of expertise include new business development and business management.
