Opinion
The Quiet Trillion: Remittances and the Illusion of Financial Sovereignty
The world’s migrants now send home more money than any aid agency or investor, and Africa’s economies are learning to live on it.

By Mark-Anthony Johnson
Every year, ministers gather at summits to debate how to rescue developing economies. They draft pledges, announce funds and promise partnerships. Meanwhile, a bus driver in London, a nurse in Houston and a laborer in Riyadh quietly wire their wages home. They never issue a communiqué, and they move more money than the summits do.
The numbers are hard to ignore. Global remittance inflows reached an estimated US$905 billion in 2024, up from roughly US$865 billion a year earlier. Half a century ago, in the late 1970s and 1980s, such transfers amounted to about 0.2 percent of global GDP. By 2024 the share had quadrupled, to roughly 0.8 percent. Along the way, remittances overtook both foreign direct investment and official development assistance as the most dependable source of external finance for the developing world. The fashionable remedies for poverty have been outperformed by something far less glamorous: the family group chat.
Africa’s $100 Billion Habit
Nowhere is the pattern starker than in Africa. Remittances to the continent reached roughly US$95 billion to US$100 billion in 2024. They work as a shock absorber against foreign-exchange shortages, and in many countries they dwarf the aid that dominates the policy conversation.
Egypt sits at the top of the table with about US$22.7 billion, which by one account exceeds what the Suez Canal and tourism earn combined. Nigeria follows with US$19.8 billion, about 38 percent of the total for Sub-Saharan Africa, sent largely from diaspora hubs in the United States and Britain. Morocco, with US$12.0 billion, owes its inflows to a vast community settled across Western Europe.
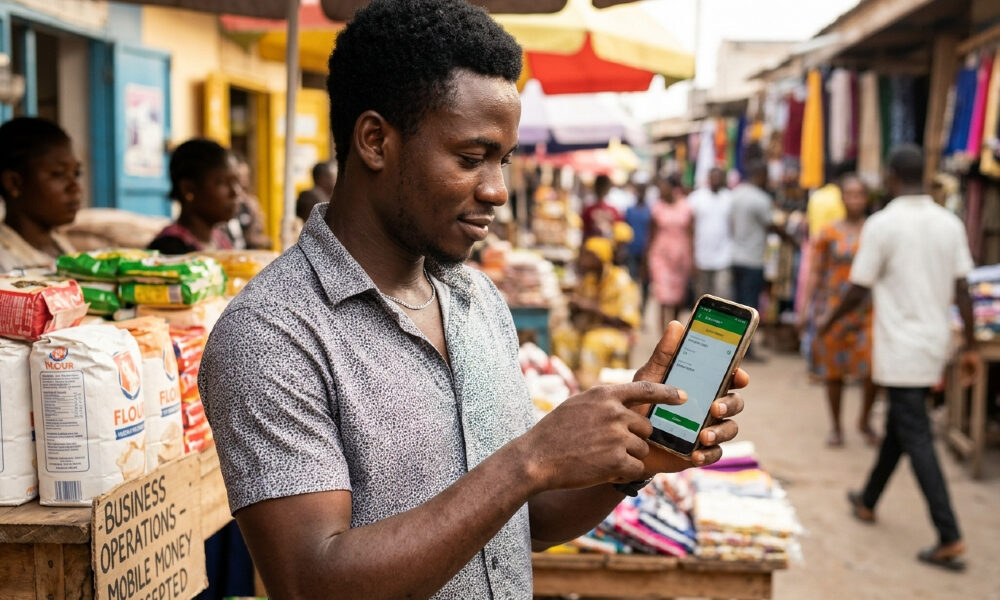
Below the leaders, the story shifts from scale to texture. Kenya (US$4.8 billion) and Ghana (US$4.6 billion) show how technology rewrites old patterns. Mobile money and digital financial-technology channels have made a transfer as easy as a text message, and cheaper to send. Senegal and Zimbabwe, at US$3.0 billion each, draw on migration corridors that run to Europe, the wider world and the factory floors and mines of neighboring South Africa. Zambia (US$2.8 billion) is rising on formalized economic ties and regional labor migration, and Uganda (US$1.5 billion) on the wages of workers in the Middle East and across the continent.
Then there is the Democratic Republic of Congo, with US$1.3 billion on the books. The recorded figure may be the least interesting part of its story. An estimated 93 percent of its remittances travel through informal channels, which means the official numbers capture only a sliver of what families actually receive.
When a Family’s Wallet Is a Country’s Economy
Dollar totals flatter the big economies. The more revealing measure is dependence, and by that yardstick the picture reverses. In Gambia, personal transfers from abroad equal 22.0 percent of GDP. In Liberia the figure is 21.2 percent. Lesotho, tethered to the South African labor market, stands at 19.9 percent, and Cape Verde, sustained by a far-flung maritime and European diaspora, at 12.3 percent.
For these countries, remittances are not a supplement to the economy. They are a pillar of it. When a fifth of national output arrives in envelopes and phone transfers, fiscal policy, exchange rates and household welfare all rise and fall with the fortunes of people living thousands of miles away.
The Uncomfortable Questions
This should prompt some humility among the architects of development policy, and some hard questions.
First, if remittances reliably outperform aid, why do rich-world governments still spend so much effort on the latter while taxing, throttling and politicizing the former? Money-transfer fees remain stubbornly high in many corridors, a levy on the poorest senders that no donor would defend if it were framed as a tax. Cutting those costs would arguably do more good than many a headline aid program.
Second, there is the paradox of dependence. A economy that runs on its emigrants is, in a sense, exporting its most ambitious citizens and importing their loyalty. Remittances sustain consumption, school fees and rent, but they rarely build factories. Countries that treat them as a permanent substitute for domestic opportunity are betting their futures on migration policies written in other capitals, where a single visa rule or recession can cut off a lifeline overnight.
Third, the data problem is a policy problem. If nine in ten Congolese remittance dollars move outside the formal system, governments cannot regulate, tax or channel them toward productive investment. Formalization is not a bureaucratic nicety. It determines whether this money is merely survived on or actually leveraged.
A Lifeline, Not a Strategy
The sensible conclusion is not to romanticize remittances. They are the triumph of ordinary people solving, one transfer at a time, problems that institutions have not. They should be respected, made cheaper and made safer. They should not be mistaken for a development plan.
The best African governments will do both: protect the flow and, with the same urgency, build economies where fewer people need to leave in order to provide for those who stay. Until then, the continent’s most reliable financier will remain the one it never invited to the summit.
Mark-Anthony Johnson is the founder and CEO of JIC Holdings, a global asset and investment management firm founded in 2009. With over 30 years of experience and strong ties to Africa, his investments span mining, infrastructure, power, shipping, commodities, agriculture, and fisheries. He is currently focused on developing farms across Africa, aiming to position the continent as the world’s breadbasket.