Business
From Market Access to Industrial Presence
The next stage of Africa strategy is not simply selling more into the continent, but deciding what capability should reside within it.

By Raymond Chimhandamba
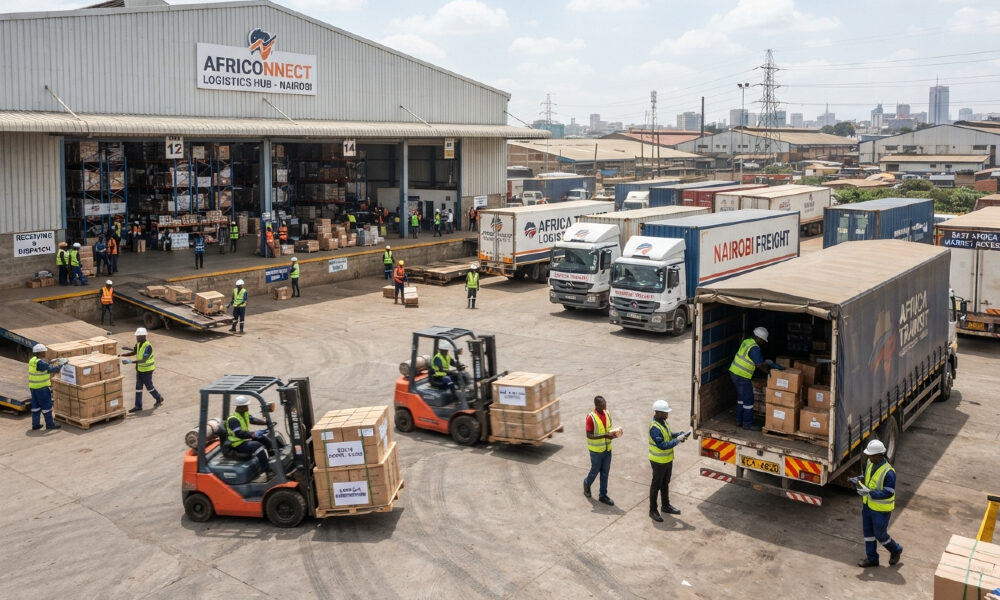
A product can be on a shelf in Lagos, Nairobi or Johannesburg while almost everything behind it sits somewhere else. The formulation, the equipment, the spare parts, the quality system, the engineering know-how and the investment decision may all be thousands of kilometers away. The company has reached the African customer. The question that matters is how much of its industrial capability has reached Africa.
I have thought about this for years, largely because I once lived inside the problem. Earlier in my career I managed a business matrix in which innovation sat in France, production and supply in Switzerland, I in South Africa, and the customers across the African continent. It was an elegant arrangement. Sophisticated products flowed into markets with different currencies, regulations and distribution systems, and European expertise could be drawn on at will. It taught me to respect a well-run international supply chain. It also taught me the difference between serving a market and building capability within it.
Market access puts a product on the shelf. Industrial presence puts capability behind it. Africa’s next chapter depends on knowing which one a company, or an investor, is actually delivering.
Prioritizing Market Access
Nothing here is meant to belittle the craft of getting a product to market. It requires far more than a shipping container and a port. Companies must master import rules, duties, currency risk, pricing and local consumer preferences. They must choose distributors wisely and then discover that the one excellent at importing is mediocre at selling, or that the one with supermarket reach has no foothold in traditional trade. A distributor with sprawling coverage may give a smaller principal scant attention while larger brands consume its resources. And everyone must, in the end, collect the money.
I have spent much of my career selecting distributors, building channels and persuading organizations with no reporting line to me to execute a shared strategy. These are hard commercial problems, and solving them is the necessary first step.
The trouble starts when the first step is mistaken for the last. A company can export profitably into Africa for years without stocking critical parts, training a single local specialist or adapting its product to local operating conditions. It can draw substantial revenue from the continent while keeping nearly all the capability behind that revenue elsewhere. It is present in the market. It is not yet present in the industrial system.
Importing vs. Building: A False Choice
Debate on this subject tends to collapse into a binary: import the product, or build a factory. This is too narrow, and it has led many a boardroom to conclude that the second option is premature and therefore to do nothing at all.
Industrial presence is a progression. It can begin with local inventory: critical materials or spare parts held in the region, which shorten lead times and let customers run with less working capital and lower supply risk. It can advance to technical support, with resident engineers, application specialists and trained service partners who solve problems without waiting for someone to fly in from another continent. Conversion, finishing and assembly can follow. Jumbo rolls can be slit to customer-specific widths, concentrates turned into finished goods, machinery configured for regional use. Eventually come local suppliers, testing capability, remanufacturing and, where volumes justify it, regional manufacturing of selected inputs or finished products.
In short: selling, stocking, supporting, adapting, converting, sourcing, manufacturing, designing. Industries will move through these stages at different speeds, and some will never need full local production. But nearly every company with a meaningful African market can ask a pointed question: should more of the capability behind our product sit closer to our customers?
Coca-Cola’s Lesson in Industrial Architecture
The Coca-Cola system offers an instructive example of how different layers of a value chain can sit at different levels. The concentrate is the proprietary core of the product, and in Southern Africa that capability has historically been concentrated in Eswatini through Conco. Bottling, by contrast, happens close to consumption. Authorized bottlers combine the concentrate with water, sweeteners and packaging, then run the warehousing, refrigeration, merchandising and distribution needed to reach thousands of formal and informal outlets.
Not every country needs a concentrate plant, and not every bottle needs to cross an ocean. The model separates what should stay concentrated from what benefits from being distributed. It guards the most valuable intellectual property while pushing production, packaging and route-to-market capability toward the consumer.
That is industrial architecture, and it carries a lesson for how Africa measures progress. Localization should not be judged only by whether a product is made from start to finish inside a single country. A value chain spread across a region can still create real jobs, skills and supplier demand in several places at once.
When Factories Outpace Materials
Africa’s hygiene-products industry shows a different, and slightly awkward, stage of the journey. Across the continent, manufacturers now produce baby diapers, sanitary pads, adult incontinence products, wipes and tissue. The finished-goods factories are increasingly present. Yet many of the critical inputs remain imported: nonwovens, superabsorbent polymers, adhesives, elastics, specialized films and some packaging.
The result is an unusual industrial shape, with local manufacturing at the tail end of the chain and a thin materials layer behind it. The answer is not to demand that every major materials supplier build a full-scale African plant tomorrow. Upstream facilities need dependable energy, infrastructure, technical skills and large amounts of capital, and demand scattered across many countries may not yet justify them.
But there are intermediate steps. A materials producer can hold regional stock, provide technical support to converters, import jumbo rolls and slit them near customers, and build local testing, recycling or application capability. It can help customers standardize specifications and aggregate regional demand. Once the market is more visible and reliable, regional manufacturing becomes far easier to justify. The real decision is not between exporting forever and building a giant plant. It is identifying the next capability that should move closer to the market.
Machines Minus Makers
Equipment suppliers illustrate the gap even more starkly. An original equipment manufacturer may have dozens, even hundreds, of machines running across Africa, installed over many years by different customers and distributors. Yet it may have no resident technical team, no regional stock of spare parts, no training center and no structured program for maintenance or upgrades.
The machines are present. The industrial capability behind them is not. When a component fails, the customer waits for a part to arrive from Europe or Asia. Operators learn by trial and error, and knowledge walks out of the door whenever an experienced technician does.
This is costly for the customer, and it is also a missed opportunity for the manufacturer. A regional service capability generates revenue from spare parts, maintenance contracts and retrofits, and it builds loyalty. It also reveals how equipment actually performs in African operating conditions, which can improve the design of the next machine. For many OEMs, the sensible first investment is not a factory. It is a map of the installed base, a shelf of the most important spares, a few well-trained technicians and dependable after-sales support.
Beyond Local Factories: True Capability
The reverse failure also exists. A plant may sit physically in Africa while its capability remains offshore. The equipment is imported, nearly every input is imported, specifications are set abroad, technical problems summon foreign engineers, and procurement decisions are made at a global head office. Local employees run the line but have little authority to modify a product, choose a supplier or improve a process.
Such a factory creates jobs and output, and assembly can be a valuable starting point for industrial development. But the more useful question is what happens next. Can local component suppliers emerge? Can maintenance and technical training move closer? Can packaging, testing or product adaptation be done locally? Can regional managers gain real authority, and can what the business learns in African markets shape its next generation of products?
A factory’s address tells you where production occurs. It does not tell you where capability lives.
Markets Over Factories: The 54-Country Case
Moving from access to presence does not mean replicating the same industrial structure in every country. African markets are wildly uneven. Some have scale but difficult logistics; others have strong ports and small domestic demand. One offers technical skills, another abundant feedstock, another cheap energy, another access to a large regional consumer base.
A sensible regional structure might have one capital-intensive manufacturing hub, several conversion or assembly sites, finishing and adaptation centers near particular markets, regional warehouses, and maintenance, training, testing and recycling capability spread according to demand.
This is where the African Continental Free Trade Area (AfCFTA) should earn its keep. Its promise is not merely that a finished product made in one country can be sold more easily in another. Its deeper promise is that different countries can perform different industrial functions inside the same regional value chain. Trade should connect African markets. Industrial strategy should connect African capabilities.
Five Questions for the Boardroom
Conventional Africa strategy begins with familiar questions: How big is the market? Who should distribute? What will customers pay? Which country first? They remain necessary. Companies seeking a durable position should add others:
- Which capabilities are currently too far from our customers?
- Where are long lead times hurting sales or customer productivity?
- Which materials, components or spare parts should be held regionally?
- What can be converted, finished or sourced closer to demand, including from African suppliers?
- Can African operating experience shape our global product design?
These questions shift Africa from a sales territory to a component of the company’s industrial system.
What Development Lenders Should Count
Development finance institutions can encourage the same shift. Jobs created, capacity installed, local ownership and capital invested all matter. None of them reveals the full industrial effect of a project.
A sharper assessment would ask whether an investment develops regional suppliers, transfers technical know-how, strengthens maintenance systems, supports testing and certification, reduces critical supply vulnerabilities or builds skills that can migrate to other industries. A plant that imports almost everything and depends on foreign technical support may still be worthwhile. But it yields a different development outcome from one that gradually builds an ecosystem around itself.
The test for a lender is simple. Is this investment merely placing an industrial asset in Africa, or is it helping industrial capability take root there? The answer should shape project design, technical assistance and the follow-on investment lenders support around the main asset.
From Sales Territory to Industrial Region
Africa’s market strategies have long been organized around access: finding distributors, crossing borders, managing risk and reaching fragmented demand. Those skills remain essential, for without them even a factory has no dependable route to its customer.
The next stage asks a harder question. Beyond how much a company can sell into Africa, which parts of its capability belong inside Africa? For one firm the answer is inventory and technical support. For another it is assembly, conversion or supplier development. For a third, regional manufacturing may already be overdue. The sequence will differ by industry. The direction should not.
Africa will not industrialize by swapping every imported product for a locally made one. Nor will it do so by staying forever dependent on materials, skills and decisions located elsewhere. The practical path lies between the extremes: placing the right capability, step by step, closer to African demand, and organizing it at the regional scale needed to stay competitive.
Market access puts a product on the shelf. Industrial presence puts capability behind it.
Raymond Chimhandamba is a Johannesburg-based consultant, writer, and speaker specializing in African industrial development, manufacturing value chains, and investment opportunities. He is director of Handas Consulting and founder of Kunakisa Recycling, with expertise in market entry, manufacturing localization, due diligence, absorbent hygiene products, nonwovens, recycling, and the commercial use of agricultural waste. He has contributed more than 40 articles to Nonwovens Industry Magazine and writes for International Fiber Journal. He also speaks at international industry events organized by INDA and EDANA. Raymond is currently writing Asymmetric Africa, a book examining overlooked opportunities in African markets.