Opinion
Beyond the Factory Floor: Why Africa Must Trap Value and Finance Productivity
Processing raw materials at home is only half the job. The other half is keeping the profits, and putting them to work, on African soil.

By Dishant Shah
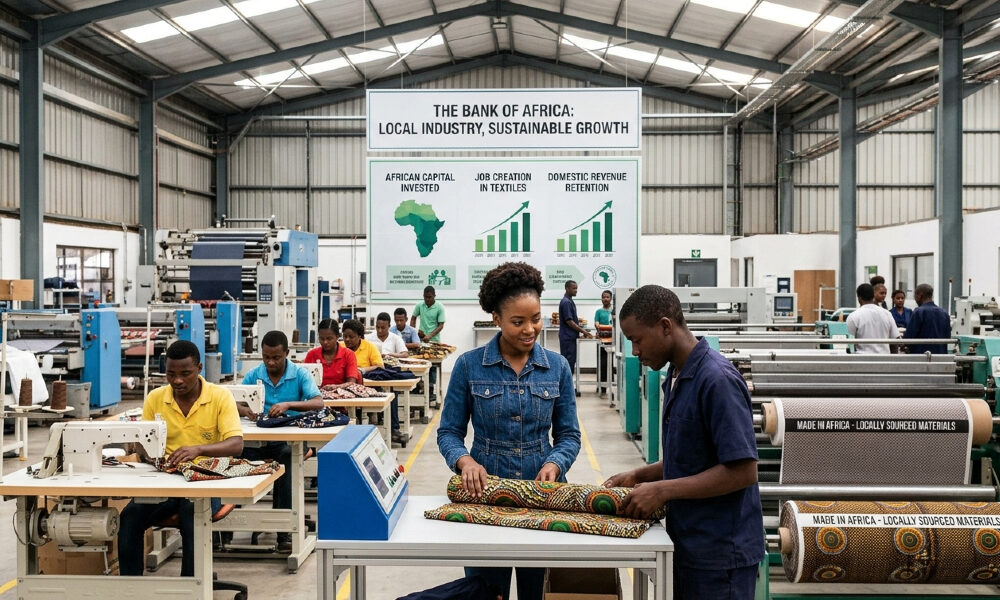
For two decades, African policymakers have pressed the case for processing at home. The logic is hard to fault. Stop shipping out raw crude, cocoa and unrefined minerals; build refineries and factories instead. On paper, it is the ultimate policy victory.
Yet a structural loophole sits in plain sight. Value addition means little if the capital it generates departs on the next flight out.
The Profit that Does not Stay
Picture a foreign conglomerate that builds a state-of-the-art plant in West or East Africa, captures the processing margin and repatriates most of the net profit to an offshore parent. What remains? A few thousand paychecks and a modest corporate tax payment.
That beats exporting raw rock. It is not structural wealth creation, however. It is a more sophisticated form of capital flight.
The Gulf states offer a useful contrast. They did not grow rich simply because petroleum lay beneath their sand. They grew rich because the revenue was anchored at home: it capitalized sovereign wealth funds and domestic banks and financed vast regional infrastructure. The money stayed in the house and worked for the house.
Africa’s leaders, industrialists and venture builders need an urgent second chapter. Real industrialization means moving the processing inside national borders, and it also means making sure the profits compound there. Without the incentives and financial plumbing to channel earnings into local capital markets and regional supply chains, Africa risks running high-margin processing hubs for other people’s balance sheets.
The Credit Gap Behind the Capital Gap
Here the story turns to credit, which is too often told as one of scarcity. The more interesting tale is the size of the demand waiting to be served.
For decades, African households and businesses have had limited access to formal credit. That is changing, though unevenly. On the consumer side, mobile money, digital banking and fintech now reach people whom traditional banks could not see. Small-ticket digital loans, salary advances, asset financing and buy-now-pay-later products are widening the definition of who can borrow.
The corporate side is more intriguing still. Africa has millions of small and medium-sized enterprises (SMEs) that need working capital to buy inventory, import machinery, finance receivables or bridge the gap between paying suppliers and getting paid by customers. Many remain underserved because conventional banks demand collateral, lengthy paperwork and financial histories that small firms do not have.
The result is peculiar: businesses with genuine economic activity that are nonetheless underbanked.
Infrastructure, not Just Lending
The opportunity lies not in lending more money but in building better credit infrastructure. Digital transaction histories, mobile payments, alternative credit scoring, trade-finance platforms, invoice financing and embedded lending can gradually turn opaque businesses and consumers into measurable credit risks.
This is the missing link in the industrialization debate. A processing plant needs a local ecosystem of suppliers, distributors and service providers, and those firms need working capital to grow alongside it. Where credit reaches them, the value created by local manufacturing multiplies and stays. Where it does not, the factory stands as an island of productivity and its profits leave.
Caveats Worth Heeding
Two warnings apply. First, Africa is not one credit market. Kenya differs from Nigeria, Nigeria from Egypt, South Africa from Ethiopia. Banking penetration, interest rates, informality, income, regulation and payment systems vary enormously, and a one-size-fits-all strategy will fail.
Second, there is the uncomfortable question of affordability. Credit that is not matched by productive capacity can turn financial inclusion into household indebtedness. The best opportunities lie where credit meets commerce: financing inventory, agriculture, housing, equipment, transport, trade and the small businesses that can turn borrowed capital into something more valuable.
Keep the Money Working at Home
Africa’s future credit appetite may have less to do with consumers wanting to borrow more than with millions of businesses finally gaining the working capital they have always needed.
So the question is not merely how much credit Africa will consume. It is how much economic activity is being held back because the financial system cannot yet see it. Until capital compounds on home turf, economic sovereignty will remain a polished conference keynote.
Dishant Shah is a partner at Legion Exim, a company specializing in facilitating the export of high-quality engineering products directly sourced from manufacturers in India to Africa. His areas of expertise include new business development and business management.