Opinion
A $220 Billion Trade Milestone Hides a Deeper Intra-Continental Divide
Intra-African trade reached a record $220 billion in 2024. But a free-trade area cannot conjure goods that nobody makes. The real challenge is not lowering borders, but building factories.

By Gregory September
Africa trades US$220 billion with itself. That is a record. It is also a small slice.
Intra-African trade reached about US$220 billion in 2024, up 12.4 percent from the year before. Yet the continent’s total goods trade was roughly US$1.5 trillion, which means some US$1.3 trillion flowed to partners elsewhere. Trade among African countries accounts for only 15 percent to 18 percent of the total. Europe, by comparison, conducts about 60 percent of its trade within its own borders.
The usual diagnosis is that Africa needs lower tariffs, and the African Continental Free Trade Area (AfCFTA) is the prescribed cure. The treatment is sound but incomplete. A free trade area cannot create goods that nobody makes. Africa’s problem is a production problem, not only a tariff problem.
Why the Share Stays Low
Five stubborn obstacles explain the gap. Transport is costly, and moving a container between neighboring capitals can cost more than shipping it across an ocean. Rules remain fragmented, with customs procedures, standards, and documentation differing at nearly every border. National markets are small, which denies firms the scale to justify investment. Many economies still depend on exporting raw commodities, which are sold to the world rather than to the neighbors next door. And the continent has too few factories making the goods that regional trade requires.
Tariff schedules touch only the first and second of these. The rest are problems of roads, rails, power, and industrial capacity. That is why corridor and processing investments will matter more than tariff schedules in determining who captures the value AfCFTA creates. A country that cuts tariffs but has nothing to sell and no way to deliver it has liberalized very little.
A Growth Story, With Caveats
The macroeconomic backdrop is encouraging. In its October 2026 World Economic Outlook, the International Monetary Fund (IMF) forecasts Sub-Saharan Africa’s economy to expand by 4.5 percent in 2026, comfortably above the global average of 3.1 percent.
The headline conceals wide variation. South Sudan leads at 10.5 percent, though that follows an astonishing 41.4 percent in 2025, a swing that says more about volatility than about momentum. Ethiopia follows at 9.2 percent and Rwanda at 7.4 percent. In West Africa, Guinea leads at 7.2 percent, with Benin and Niger at 7.0 percent each. Nigeria accelerates to 4.2 percent, while Ghana slows to 5.2 percent. In North Africa, Sudan leads at 7.0 percent and Egypt reaches 5.1 percent, while Libya faces the sharpest slowdown, from 15.9 percent to 3.3 percent.
East Africa is the most consistently strong region: Uganda is projected at 6.2 percent and Tanzania at 6.0 percent. Kenya, at 4.5 percent, matches the regional average. In Southern Africa, Zambia accelerates to 5.6 percent and Botswana rebounds from a 0.7 percent contraction to 4.4 percent, while South Africa, the continent’s most industrialized economy, limps along at 1.0 percent. At the bottom, Equatorial Guinea is forecast to contract by 1.7 percent, São Tomé and Príncipe to grow just 0.4 percent, and Mozambique and Seychelles 1.0 percent each.
The IMF credits stronger policy frameworks and structural reforms for supporting parts of the continent. It warns that elevated energy prices, geopolitical disruptions, tighter financing conditions, and external vulnerabilities weigh on fuel-importing economies.
Growth Isn’t a Thesis
A 4.5 percent regional forecast is not an investment thesis. It is a starting question: which economies can convert growth into durable returns?
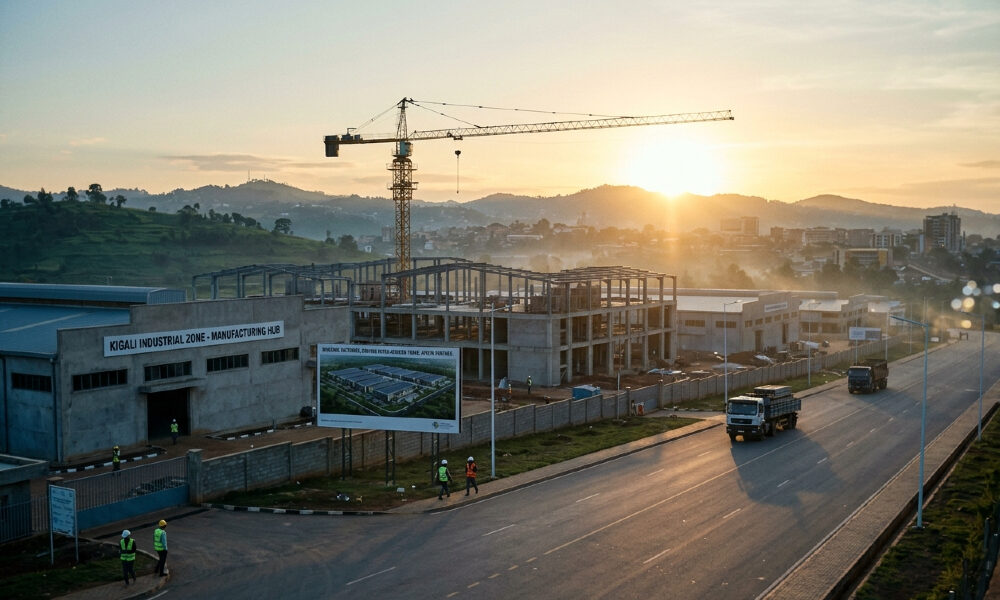
The answer is rarely the fastest grower. Growth driven by a commodity windfall, or by recovery from a collapse, can evaporate as quickly as it arrived. Libya’s slide from 15.9 percent to 3.3 percent is the cautionary tale. Durable returns come from economies that turn output into diversified production, and that is precisely where regional trade matters. A factory in Kigali or Addis Ababa that can sell to 1.4 billion Africans rather than 14 million Rwandans has a different cost of capital, a different scale, and a different future.
This is the link between trade and the global development agenda. More regional trade builds jobs, which is the aim of Sustainable Development Goal (SDG) 8. Roads, rail, and factories make that trade possible, which is SDG 9. And regional markets need shared rules and cooperation to function, which is SDG 17. The goals are not decorative. They describe the same chain of causation, running from infrastructure to production to trade to employment.
Factories First
So what should come first: lower tariffs or more factories?
The honest answer is that the question is a false choice, but the sequencing is not. Tariff cuts without productive capacity redistribute a small pool of goods. Factories without open borders strand their output in small domestic markets. Yet if policymakers must prioritize scarce political capital and scarce capital, the greater return lies in the physical and industrial foundations: corridors that cut transit times, power that keeps plants running, and processing capacity that lets Africa keep more of the value it currently ships abroad as raw material.
Africa’s trade with itself has never been higher. The task now is to make sure there is more to trade.
Gregory September is a South African academic, author, and geopolitical analyst with extensive experience in government and Parliament. He is the founder and CEO of SAUP (Sustainability Awareness and Upliftment Projects NPC), which focuses on sustainability education and community development. He previously served as Head of Research and Development for the Parliament of South Africa. His work centers on sustainability, African geopolitics, and economic development, and he regularly contributes to analysis of global political and economic affairs.